New Freddie Mac Requirements Put Energize Denver Compliance in the Lending Spotlight
New Freddie Mac Requirements Put Energize Denver Compliance in the Lending Spotlight
A recent Freddie Mac update signals that building performance requirements are beginning to affect underwriting, disclosure, and escrow expectations for multifamily financing in Denver. For CREDA members who are owners, borrowers, lenders, and investors, the development raises important questions about capital availability, compliance planning, and the broader impact of Energize Denver and Colorado Regulation 28.
According to the update, borrowers must now demonstrate that they have submitted required benchmarking data, and if a property is not on track to comply, Freddie Mac will require a compliance plan outlining the estimated costs and timeline to achieve compliance. Freddie Mac may also require funds to be escrowed as part of the financing. Currently, we believe this may impact approximately 80 existing loans
CREDA Colorado wants to make you aware of a concerning development related to Energize Denver.
See these links for more details:
- Freddie Mac Guide Bulletin | Linked Here
- Freddie Mac Business Update | Linked Here
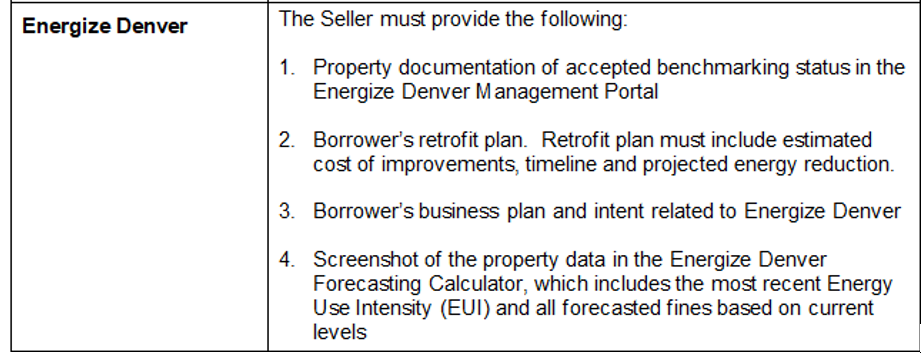
The primary concern is that Fannie Mae and other commercial lenders may follow Freddie Mac's lead. If that happens, the implications could extend well beyond multifamily housing and have a chilling effect on capital availability and investment activity throughout Denver.
Freddie Mac's current requirements reference Energize Denver but do not require disclosure related to Colorado's Regulation 28. Because the two building performance standards overlap, Regulation 28 may eventually become part of lender due diligence requirements as well.
CREDA will continue to monitor how these lending requirements may affect its federal lawsuit challenging Energize Denver and Regulation 28.
We would appreciate hearing from members, owners, borrowers, lenders, or financing partners who encounter similar disclosure requirements, underwriting changes, compliance questions, or escrow requirements. Documented examples could be valuable for advocacy efforts and as evidence in the ongoing litigation.
CREDA Colorado will continue tracking these developments and sharing updates as the lending and regulatory landscape evolves.